Medicaid Waiver Payments: A Guide to Tax Rules for Caregivers
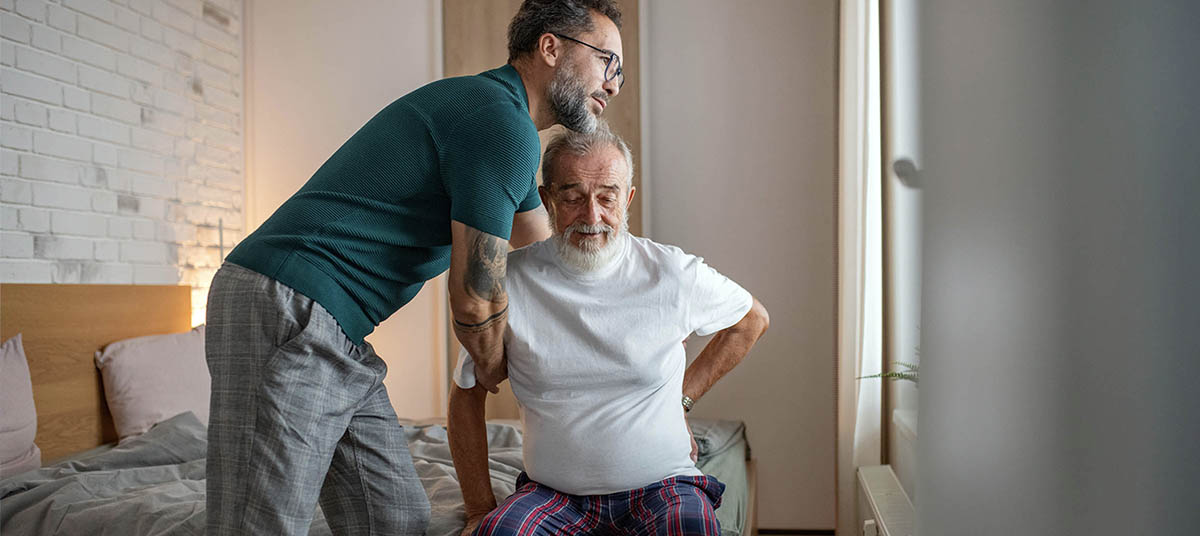
Medicaed waiver payments sit at a complex intersection of health care, social services, and tax regulations. For many family caregivers, these payments represent more than just compensation for daily care. They can also significantly impact eligibility for key tax benefits, such as the Earned Income Tax Credit (EITC) and the Additional Child Tax Credit (ACTC). Navigating these rules requires a clear understanding of what these payments are, who is eligible to receive them, when they are excluded from taxable income, and how they can still be utilized as earned income for tax credits.
Tax treatment of these payments is governed by specific IRS guidance and pivotal court rulings. Given the nuances involved, caregivers must approach their tax preparation with care and precision to ensure they remain compliant while claiming every credit to which they are legally entitled.
Understanding Medicaid Waiver Payments
Medicaid waiver payments are distributed under state-approved programs designed to allow individuals with chronic needs or disabilities to receive care in their own homes or communities rather than in institutional facilities. In practice, these funds are typically paid to family members or other designated caregivers who provide what the tax code refers to as “difficulty of care” services.
These programs were established with a clear objective: to reduce reliance on institutional facilities and support independent living within a familiar environment. For caregivers, the compensation offsets the substantial time and financial costs associated with providing constant care. From a public policy perspective, these waivers improve quality of life for care recipients while easing the financial burden on families who would otherwise have to pay for external care facilities.
Who Qualifies for the Tax Exclusion?
Qualification for favorable tax treatment depends heavily on both the structure of the state waiver program and the living arrangements of those involved. To qualify for the income tax exclusion, the caregiver must be providing services under an approved state Medicaid waiver program.
Additionally, there is a strict home-sharing requirement. The caregiver and the care recipient must reside in the same household. This can be either the home of the caregiver or the home of the care recipient. If the care provider and care recipient do not live together in the exact same residence, the payments cannot be excluded from gross income and are fully taxable. This distinction is a frequent source of reporting errors for taxpayers who assume all Medicaid waiver payments are automatically tax-free.
Taxability and Notice 2014-7
Under IRS Notice 2014-7, qualified Medicaid waiver payments meet the necessary criteria to be excluded from gross income for federal tax purposes. When the same-home residency requirement is satisfied, these payments are not reported as taxable income on a federal return.
However, if the residency requirement is not met, the payments must be treated as fully taxable income. This makes establishing and documenting the shared living arrangement critical for accurate tax filing. Even when these payments are properly excluded from gross income, taxpayers should understand that the tax code permits these same funds to be treated as earned income when calculating specific tax credits.
Navigating W-2 Reporting and Documentation Issues
Reporting Medicaid waiver payments can be confusing due to variations in how they are documented. Some taxpayers receive a Form W-2 showing these payments in Box 12 alongside code II. This code indicates that the payments are excluded from gross income under IRS Notice 2014-7. However, this exclusion does not mean the income is entirely irrelevant for tax purposes; caregivers may still opt to count this amount as earned income to qualify for the EITC and ACTC.
Further complications arise in states utilizing self-certification systems, where caregivers may not receive a W-2 at all. When no official form is issued, maintaining meticulous records of all payments received is essential. These records are necessary for verifying income amounts when preparing current returns or when amending prior-year filings to claim overlooked credits.
Utilizing Excluded Payments for the EITC and ACTC
Initially, the IRS maintained that tax-excluded Medicaid waiver payments could not be treated as earned income for the purpose of claiming the EITC or the ACTC. This position changed following the landmark Tax Court case involving Mary and Edward Feigh. The Feighs received Medicaid waiver payments for providing care to their disabled adult children in their home. While they excluded the payments from their gross income, they still reported them as earned income to claim the EITC and ACTC.
When the IRS challenged this treatment, the Tax Court ruled in favor of the Feighs. The IRS subsequently acquiesced to the decision, confirming that caregivers may choose to treat qualified, excluded Medicaid waiver payments as earned income for these tax credits.
For married couples filing jointly where both spouses receive qualified waiver payments, the tax rules allow for individual flexibility. Each spouse has the right to make an independent election regarding whether to include their specific waiver payments in the earned income calculation. This separate election option allows couples to optimize their overall EITC calculation.
Amending Prior-Year Tax Returns for Refunds
Caregivers who did not previously utilize their Medicaid waiver payments to claim the EITC or ACTC may be eligible to file amended tax returns to claim a refund. This opportunity is available for tax years that remain open under the federal refund statute of limitations.
Generally, the statute of limitations for securing a federal tax refund is three years from the date the original return was filed (or its original filing deadline, whichever is later), or two years from the date the tax was paid, whichever is later. Amending past returns to include qualified payments as earned income can result in significant tax refunds for households that previously underclaimed these credits or had them denied.
How Montana Families Can Plan with Confidence
Understanding the exact tax treatment of Medicaid waiver payments is essential for safeguarding your family's financial stability. When you and the care recipient share a household, the payments can be excluded from gross income while still serving as earned income to secure valuable tax credits like the EITC and ACTC. Following the precedent set by the Feigh case and the IRS's subsequent guidance, caregivers have clear, legal paths to optimize their tax positions.
Because these rules depend heavily on specific household structures, residency documentation, and program guidelines, personalized review is highly beneficial. If you have questions about how these payments impact your tax return, or if you want to explore amending prior-year filings for a refund, contact our office to schedule a consultation.
Want tax & accounting tips and insights?
Sign up for our newsletter.